Indonesia’s Pawnshop Industry Surges in 2026: Financing Reaches IDR 160.78 Trillion Amid High Demand and Luxury Sector Boom
JAKARTA — The Indonesian pawnbroking industry has demonstrated unprecedented growth momentum, cementing its critical role as an agile financial safety net and an alternative liquidity engine for both retail consumers and high-net-worth individuals. According to the latest official figures released by the Financial Services Authority (Otoritas Jasa Keuangan – OJK), total financing channeled by the national pawnbroking industry skyrocketed to IDR 160.78 trillion as of July 2026. This represents a staggering year-on-year (yoy) surge of 50.73%, reflecting a fundamental shift in how diverse segments of society approach short-term capital, asset leveraging, and emergency liquidity.
This explosive expansion highlights the evolving sophistication of the sector. Far from being viewed merely as a traditional lender of last resort, the modern Indonesian pawnbroking ecosystem has evolved into a dynamic financial sub-sector capable of servicing everyone from micro-entrepreneurs seeking working capital to ultra-wealthy collectors unlocking multi-billion-rupiah liquidity through luxury assets. However, this high-growth environment also brings complex regulatory challenges, heightened risk profiles, and a pressing need for institutional governance and disciplined risk management.
Main Facts: The Anatomy of the 2026 Pawnbroking Boom
The OJK data for July 2026 paints a vivid picture of a sector expanding at breakneck speed. The primary driver behind this IDR 160.78 trillion milestone remains the core traditional pawning product (Gadai), which accounts for the lion’s share of the market.
- Total Outstanding Financing: IDR 160.78 trillion (a 50.73% yoy increase).
- Core Product Dominance: Traditional Gadai instruments reached IDR 136.39 trillion, capturing an overwhelming 84.83% of the total financing portfolio across the national industry.
- Growth Catalysts: Accelerated branch network expansions, wider geographical penetration by licensed operators, and an insatiable public appetite for rapid, low-friction financing solutions.
- Emerging Segments: Rapid adoption of asset-backed lending within the luxury pawn (luxury pawn) segment, catering to High Net Worth Individuals (HNWIs), business owners, and elite collectors.
The dominance of core Gadai products at nearly 85% demonstrates that everyday consumers and small-scale business owners continue to rely heavily on physical collateral—ranging from gold jewelry and electronics to vehicles—to bridge cash flow gaps. Simultaneously, the remaining percentage of the portfolio has increasingly diversified into non-traditional, high-value assets, signaling a structural maturation of the broader alternative lending market in Indonesia.
Chronology: The Path to Exponential Growth
To understand how the Indonesian pawnbroking industry reached this monumental milestone in mid-2026, it is essential to trace the strategic and economic milestones that shaped the sector over the preceding years:
Post-Pandemic Economic Normalization (2022–2023)
As the Indonesian economy emerged from the disruptions of the global health crisis, small and medium enterprises (SMEs) faced severe working capital constraints. Traditional banking institutions, constrained by strict prudential banking regulations and lengthy bureaucratic vetting processes, struggled to disburse micro-loans quickly enough to meet urgent business demands. Licensed pawnbrokers stepped into this vacuum, offering immediate, collateral-based cash disbursements without requiring complex credit scoring models.
Regulatory Formalization and Digitization (2024–2025)
Recognizing the rapid proliferation of both state-owned and private pawnbroking entities, the OJK implemented stricter licensing frameworks under the purview of the Chief Executive of Supervision for Financing Institutions, Venture Capital Companies, Microfinance Institutions, and Other Financial Services Institutions (PVML). Concurrently, major industry players aggressively digitized their operations. Mobile applications for loan valuations, digital storage tracking, and online interest payments reduced friction, attracting a younger, tech-savvy demographic of borrowers.
The 2026 Liquidity Crunch and Luxury Pivot (Early 2026)
By the first half of 2026, macroeconomic pressures—including fluctuating global commodity prices and tighter monetary policies—prompted both retail borrowers and affluent business owners to seek alternative liquidity channels that avoided the rigidity of commercial bank loans. This macro backdrop set the stage for the July 2026 data release, where financing volumes broke previous historical ceilings, driven equally by grassroots demand for traditional micro-loans and high-end liquidity provisioning for luxury assets.
Supporting Data: Portfolio Breakdown and Market Dynamics
A deeper dive into the market mechanics reveals distinct tiers within Indonesia’s pawnbroking landscape. While state-backed giants like PT Pegadaian continue to command the vast majority of physical footprints and overall asset volumes, private pawnbroking firms have carved out highly lucrative, specialized niches.
The Mass Market vs. The Elite Niche
The market is broadly bifurcated:
- The Mass Retail Segment: Driven by traditional gold and household asset pledging. Gold remains the undisputed king of collateral in Indonesia due to its high liquidity, stable long-term value, and deep cultural resonance.
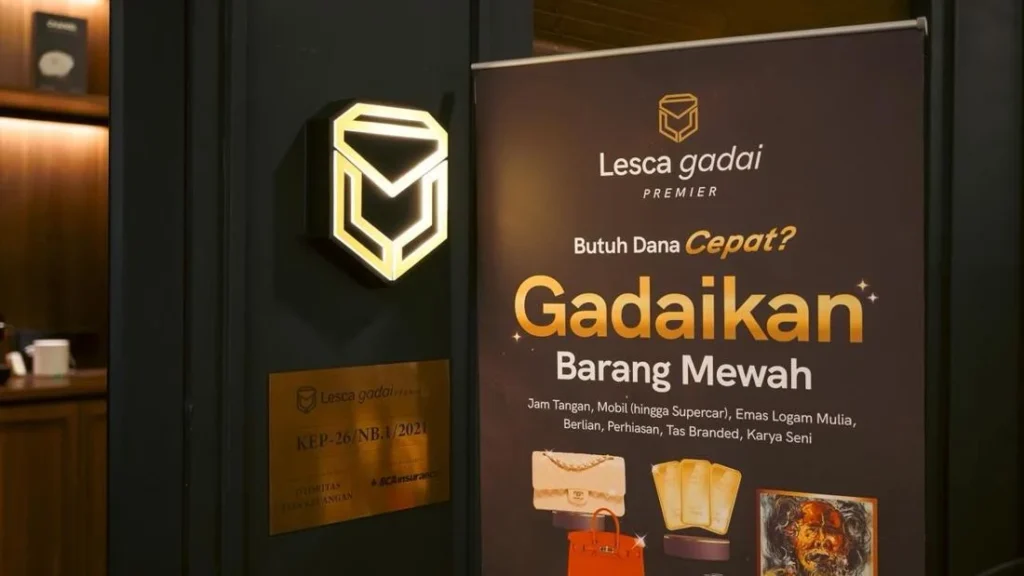
- The Luxury Asset Segment (Luxury Pawn): A rapidly expanding niche dominated by high-end private operators. This segment targets HNWIs, corporate executives, and collectors who hold idle high-value assets—such as Swiss luxury timepieces (Rolex, Patek Philippe, Audemars Piguet), hypercars, fine art, designer handbags (Hermès, Chanel), and precious gemstones.
Asset-Backed Lending as a Corporate Strategy
For many Indonesian entrepreneurs, liquidating capital tied up in luxury assets through traditional banking channels can take weeks or months, often requiring extensive financial disclosures and corporate audits. Asset-backed lending via premier pawnshops allows these individuals to secure multi-billion-rupiah working capital injections within hours.
[Borrower: HNWI / Entrepreneur]
       │
       ▼ (Submits Luxury Asset: Watch, Art, Supercar)
[Professional Appraiser / ISO-Certified Vault]
       │
       ▼ (Valuation based on International Secondary Markets)
[Instant Disbursement: Up to Billions of Rupiah]
       │
       ▼ (Asset Retained Safely; Ownership Preserved)
As Bastian Purnama, Director of PT Lesca Gadai Premier, noted, this mechanism acts as an indispensable bridge for business owners. "Through the premium pawning scheme, customers can optimize the latent liquidity of their collections up to billions of rupiah to capture new business opportunities, while full ownership of the asset remains completely preserved," Purnama explained.
Official Responses and Regulatory Guidance
The phenomenal growth figures have naturally drawn the keen attention of regulatory authorities. While the OJK welcomes the financial inclusion and liquidity benefits provided by the industry, systemic expansion brings inherent operational hazards.
OJK’s Cautionary Stance on Risk Management
Agusman, the OJK’s Chief Executive of PVML Supervision, emphasized that while the quantitative growth is commendable, institutions must not lose sight of fundamental risk disciplines. Rapid expansion without adequate internal controls can expose lenders to severe market shocks.
"Pelaku usaha perlu mencermati kualitas serta pergerakan harga agunan yang mempengaruhi risiko usaha, di samping tantangan akses dan efisiensi biaya pendanaan yang masih dihadapi oleh pergadaian swasta dalam memperluas pembiayaannya," Agusman stated, urging industry players to remain vigilant as of Monday (21/9/2026).
Agusman specifically highlighted two critical vulnerabilities facing the sector:
- Collateral Price Volatility: Fluctuations in the market value of pledged assets (particularly gold and luxury goods) can quickly erode the safety buffer of outstanding loans, leading to potential default losses if LTV (Loan-to-Value) ratios are improperly managed.
- Funding Access and Cost Efficiency: Private pawnbrokers often face higher costs of capital compared to commercial banks or state-backed giants, making efficient treasury management and liquidity forecasting essential for survival.
Private Sector Alignment with Global Standards
Responding directly to regulatory concerns regarding asset volatility and risk mitigation, private operators have moved swiftly to adopt institutional-grade compliance and security frameworks.
PT Lesca Gadai Premier, for instance, has anchored its operational model on rigorous international benchmarks. The company utilizes certified professional appraisers who cross-reference item valuations against live international secondary market databases. Furthermore, the firm has secured dual international certifications: ISO 9001:2015 (Quality Management Systems) and ISO/IEC 27001:2022 (Information Security Management Systems). These accreditations aim to reassure both regulators and high-net-worth clients that high-value physical assets are handled with absolute security, transparency, and professional accountability.
Implications: The Future of Indonesia’s Alternative Financing Ecosystem
The trajectory of Indonesia’s pawnbroking industry through mid-2026 carries profound implications for the broader national economy, financial stability, and regulatory landscape.
1. Deepening Financial Inclusion and Agility
By providing rapid, collateral-based liquidity, pawnbrokers absorb the economic shocks experienced by segments of the population that lack formal credit histories. As traditional banks tighten underwriting criteria amid global economic uncertainties, pawnbrokers serve as an indispensable shock absorber for micro-entrepreneurs and SMEs, keeping grassroots commerce fluid.
2. Maturation of the Luxury Secondary Market
The rise of luxury pawning is fostering a more sophisticated secondary market for high-end goods in Indonesia. With professional appraisal firms utilizing international databases, the valuation of luxury assets is becoming increasingly transparent. This reduces fraud risks and enhances consumer confidence in alternative financial instruments.
3. Heightened Regulatory Oversight
Given that total industry financing has crossed the IDR 160 trillion threshold, the OJK is expected to intensify supervisory measures. Future regulatory updates may focus on mandatory capital adequacy ratios for private pawnbrokers, stricter digital security compliance for online loan platforms, and standardized asset-appraisal protocols to protect consumers against predatory valuation practices.
4. Competitive Dynamics Between State and Private Lenders
While PT Pegadaian maintains structural dominance through its vast state-backed network, agile private operators specializing in high-end, bespoke financing are carving out profitable niches. This competition ultimately benefits consumers, driving down interest rates, improving customer service standards, and accelerating technological adoption across the entire sector.
Conclusion
The Indonesian pawnbroking industry’s achievement of IDR 160.78 trillion in financing by July 2026 marks a watershed moment in the nation’s financial history. Driven by a 50.73% yoy growth rate, the sector has proven its dual capability: serving as a vital micro-financing lifeline for everyday citizens while simultaneously unlocking multi-billion-rupiah liquidity for Indonesia’s economic elite through sophisticated luxury asset-backed lending.
However, as OJK’s warnings underscore, maintaining this explosive trajectory requires uncompromising adherence to risk management, professional asset valuation, and stringent regulatory compliance. As the industry moves into the latter half of 2026 and beyond, the ability of both state and private pawnbrokers to balance rapid expansion with institutional prudence will determine whether this remarkable financial boom translates into long-term, sustainable economic stability for Indonesia.