OJK Secures Historic IDR 2.1 Trillion Capital Market Fine, Bolstering Investor Trust and Regulatory Enforcement
JAKARTA — In a landmark development for Indonesia’s financial regulatory landscape, the Financial Services Authority (Otoritas Jasa Keuangan or OJK) has successfully collected a staggering IDR 2.1 trillion in fines resulting from major capital market violations. The milestone payment, finalized just two days prior to the announcement, marks a decisive victory for regulatory compliance, transparency, and market integrity in Southeast Asia’s largest economy.
The penalties stem from high-profile infractions involving three major corporate entities listed on the Indonesia Stock Exchange (IDX): PT Dian Swastatika Sentosa Tbk (DSSA), PT Barito Renewables Energy Tbk (BREN), and PT Petrindo Jaya Kreasi Tbk (CUAN).
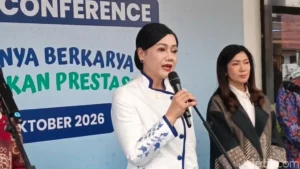
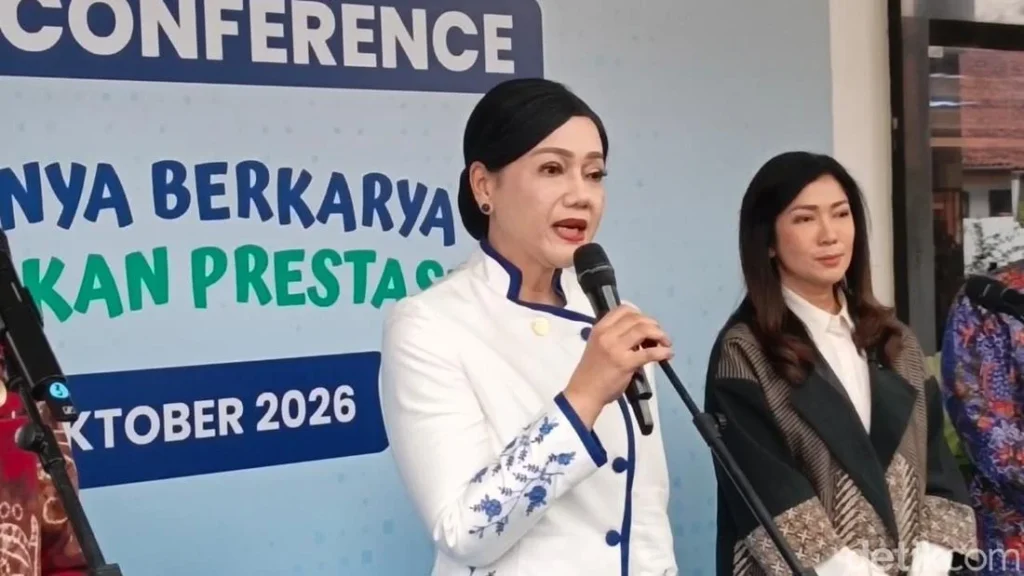
The successful enforcement action was formally confirmed by Friderica Widyasari Dewi, Chairperson of the Board of Commissioners of the OJK, during a press briefing held at the Hotel Borobudur in Jakarta. Speaking to journalists, Kiki—as she is affectionately known within Indonesian financial circles—highlighted the sheer scale of the penalty collection with a touch of levity.
"They have paid two days ago. We should have invited you [the media] to come and see the money. A total of IDR 2.1 trillion has been paid," Kiki remarked to reporters, underscoring the magnitude of the enforcement action.
This comprehensive report delves into the intricate details of the enforcement action, the chronological breakdown of the cases, the supporting data surrounding the penalties, official responses from regulatory bodies, and the broader implications for Indonesia’s capital market trajectory, global investor sentiment, and domestic market stability.
1. Main Facts: The IDR 2.1 Trillion Enforcement Breakdown
The IDR 2.1 trillion penalty represents one of the largest aggregate collections of administrative fines in the history of the Indonesian capital market. The enforcement actions were the culmination of rigorous joint investigations conducted by the OJK in active coordination with the Indonesian National Police’s Criminal Investigation Agency (Bareskrim Polri).
The fines were distributed across three separate, high-stakes cases involving distinct corporate entities and institutional actors:
- PT Dian Swastatika Sentosa Tbk (DSSA) Case: The largest single penalty within this enforcement wave was levied against PT SMT, which was handed an administrative fine of IDR 1.5 trillion for severe capital market violations connected to DSSA share trading activities.
- PT Barito Renewables Energy Tbk (BREN) Case: In connection with irregularities surrounding its public share offering, an administrative fine of IDR 500 billion was imposed upon an overseas corporate entity identified by the initials AH Ltd. The firm was found to have engaged in the deliberate obfuscation of the true identities of parties placing share orders for BREN, violating foundational disclosure and transparency mandates.
- PT Petrindo Jaya Kreasi Tbk (CUAN) Case: Mirroring the BREN infraction, an international corporate entity designated as TC Pte Ltd was penalized with a IDR 100 billion fine for parallel violations regarding obscured share ownership during its public offering. Additionally, two securities brokerages acting as underwriting agents (Anggota Bursa or AB)—identified as PT HPS and PT BDS—faced administrative fines for regulatory and procedural violations tied to the CUAN offering.
Together, these penalties culminate in the historic IDR 2.1 trillion figure, demonstrating the OJK’s unyielding stance against market manipulation, opacity, and regulatory arbitrage.
2. Chronology: Unraveling the Violations and Regulatory Crackdown
The journey toward the collection of this monumental fine began months prior, rooted in comprehensive market surveillance by the OJK. As Indonesia’s capital markets experienced rapid post-pandemic growth, alongside a surge in Initial Public Offerings (IPOs) and heavy trading volumes in prominent energy and diversified holding conglomerates, regulatory scrutiny intensified.
Phase 1: Surveillance and Anomaly Detection
Market surveillance teams within the OJK flagged unusual trading patterns and transactional complexities associated with the share distributions of DSSA, BREN, and CUAN. Cross-border capital movements, layered ownership structures, and nominee arrangements quickly drew the attention of regulators. Under Indonesian capital market laws, transparency regarding the ultimate beneficial owners and actual purchasers of shares during public offerings is non-negotiable.
Phase 2: Joint Investigations with Bareskrim Polri
Recognizing the sophisticated nature of the financial engineering involved—particularly concerning entities incorporated outside traditional domestic oversight—the OJK escalated the matter. Partnering directly with Bareskrim Polri, investigators launched a joint probe to untangle the web of transactions. This collaboration allowed regulatory administrators to leverage law enforcement investigative tools, subpoena powers, and cross-border intelligence-sharing networks.
Phase 3: Sanction Announcements and Adjudication
Following the conclusion of the investigations, the OJK, alongside Bareskrim Polri, formally announced administrative sanctions against the culpable parties. The legal foundation for these actions was anchored heavily in Article 107 of the Capital Market Law (UU PM), as amended by Article 22, number 48 of the Law on the Development and Strengthening of the Financial Sector (UU PPSK). This statutory framework grants regulators robust powers to penalize entities that obscure information, engage in fraudulent market practices, or compromise the fair and orderly operation of the stock exchange.
Phase 4: Compliance and Final Settlement
Despite the severity of the charges and the unprecedented scale of the fines, the targeted entities complied with the OJK’s administrative mandates. The final settlement was wired and cleared just two days prior to the public announcement in late October 2026, marking a swift closure to a potentially protracted legal battle and reinforcing the supremacy of regulatory enforcement in Indonesia.
3. Supporting Data: Legal Frameworks and Specific Penalties
To fully comprehend the significance of the OJK’s action, it is essential to examine the precise legal violations and the corresponding financial penalties levied against each institutional actor.
Legal Basis: UU PM and UU PPSK
The primary statutory weapon utilized by the OJK in these cases is Article 107 of the Capital Market Law (Law No. 8 of 1995 concerning Capital Markets), updated and reinforced by Article 22 number 48 of Law No. 4 of 2023 concerning the Development and Strengthening of the Financial Sector (UU PPSK).
This legal provision criminalizes and penalizes actions that create false or misleading appearances regarding market activity, stock prices, or the distribution of securities during public offerings. Specifically, the law cracks down on "nominee accounts" or hidden order placements designed to mask the identity of the true economic beneficiaries of large block trades or IPO allocations.
Detailed Breakdown of Sanctions
| Case / Issuer | Entity Sanctioned | Type of Violation | Penalty Amount | Legal Reference |
|---|---|---|---|---|
| PT Dian Swastatika Sentosa Tbk (DSSA) | PT SMT | Violations related to share trading activities | IDR 1.5 Trillion | Capital Market Regulations & Enforcement Guidelines |
| PT Barito Renewables Energy Tbk (BREN) | AH Ltd. | Obfuscation of information regarding parties ordering share allocations | IDR 500 Billion | Article 107 UU PM jo. Article 22 point 48 UU PPSK |
| PT Petrindo Jaya Kreasi Tbk (CUAN) | TC Pte Ltd. | Obfuscation of information regarding parties ordering share allocations | IDR 100 Billion | Article 107 UU PM jo. Article 22 point 48 UU PPSK |
| PT Petrindo Jaya Kreasi Tbk (CUAN) | PT HPS & PT BDS | Administrative and procedural broker-dealer (Anggota Bursa) violations | Undisclosed (Administrative Fines) | Brokerage Compliance Regulations |
The inclusion of international corporate entities (such as AH Ltd. and TC Pte Ltd.) highlights the OJK’s expanding extraterritorial reach and its determination to police cross-border financial flows that impact the domestic exchange.
4. Official Responses: OJK’s Vision for Market Reform
The successful collection of the IDR 2.1 trillion penalty serves as a centerpiece for the OJK’s broader strategic narrative: a relentless commitment to cleaning up, modernizing, and reforming the Indonesian capital market.
Reassuring Global Investors
During her address at Hotel Borobudur, Friderica Widyasari Dewi emphasized that this high-profile enforcement action is not merely punitive, but transformative. The OJK is actively engaged in continuous dialogues with international institutional investors, sovereign wealth funds, and global asset managers to articulate the structural and regulatory reforms underway in Indonesia.
Global investors have historically voiced concerns regarding market transparency, minority shareholder rights, and the prevention of price manipulation in emerging markets. By demonstrating that the OJK can successfully investigate, prosecute, and collect multi-trillion-rupiah fines from violators—regardless of their corporate stature or geographic origin—the regulatory body sends a powerful signal that Jakarta is serious about maintaining a clean, rules-based financial ecosystem.
Championing the Domestic Retail Investor Base
While wooing global capital remains a top priority, Kiki was careful to emphasize the irreplaceable role of domestic retail investors in anchoring the stability of the Indonesian stock market. Over the past half-decade, Indonesia has witnessed an unprecedented boom in retail investor participation, driven by digital brokerages, financial literacy campaigns, and youth engagement.
"So we continue to try to convince [investors] about the reforms we are carrying out. Indonesia’s economic fundamentals are strong, solid, and we must also support [the market], especially if I may also ask for the support of Indonesian retail investors," Kiki stated emphatically.
The OJK views the retail community not just as market participants, but as vital guardians of market liquidity and long-term economic resilience. Protecting these retail investors from opaque market practices and hidden manipulation is framed as a moral and structural imperative for the regulator.
5. Implications: What IDR 2.1 Trillion Means for Indonesia’s Financial Future
The resolution of the DSSA, BREN, and CUAN enforcement cases carries profound implications for the future trajectory of Indonesia’s capital market, corporate governance standards, and regulatory oversight.
1. A Paradigm Shift in Regulatory Deterrence
For years, critics of emerging market regulators often pointed to a perceived "barking without biting" phenomenon, where penalties were either too lenient to deter multi-million-dollar infractions or bogged down indefinitely in administrative appeals. The swift payment of IDR 2.1 trillion shatters this perception. It establishes a new benchmark for regulatory deterrence in Indonesia, proving that the OJK—backed by law enforcement—possesses the institutional teeth to enforce compliance on an unprecedented scale.
2. Enhanced Corporate Governance and Disclosure Standards
Listed corporations and underwriting syndicates operating on the Indonesia Stock Exchange (IDX) are now forced to re-evaluate their compliance frameworks. The severe penalties handed down for obfuscating share orders in the BREN and CUAN cases serve as a stark warning: attempts to conceal beneficial ownership, utilize complex offshore nominee structures, or bypass disclosure rules will face severe, existential financial consequences. Consequently, Indonesian corporations are expected to adopt vastly more rigorous internal compliance, legal vetting, and transparency protocols.
3. Strengthening Indonesia’s Global Investment Grading and Appeal
As international capital flows increasingly prioritize Environmental, Social, and Governance (ESG) standards alongside corporate transparency, regulatory credibility is a critical component of a country’s investment grade appeal. By taking decisive action against high-profile market infractions, the OJK reassures foreign institutional investors that the IDX is maturing into a transparent, highly regulated market capable of protecting foreign and domestic capital alike. This could pave the way for increased foreign portfolio inflows and higher weightings for Indonesian equities in global benchmark indices.
4. Fortifying Domestic Market Resilience
Domestic retail investors, who have become the backbone of daily trading volume on the IDX during periods of global macroeconomic volatility, stand to benefit immensely from a cleaner marketplace. Market integrity directly translates to investor confidence. When retail participants trust that market prices reflect genuine supply and demand rather than manufactured manipulation or hidden order routing, market participation deepens, fostering long-term wealth creation for Indonesian households.
Conclusion
The OJK’s successful collection of IDR 2.1 trillion in capital market fines marks a watershed moment for Indonesia’s financial sector. By holding powerful corporate actors and offshore entities accountable for violations in the DSSA, BREN, and CUAN cases, the regulatory body has demonstrated an uncompromising commitment to market integrity.
As Chairperson Friderica Widyasari Dewi and her team press forward with comprehensive capital market reforms, the message to domestic and international stakeholders is unequivocal: Indonesia’s financial markets are open for transparent, rules-based business, and regulatory impunity is officially a thing of the past.